
We already know that starting to invest has the advantage that the best time is now. But that doesn’t mean we should rush. Nor take unnecessary risks. In this series of posts about investment, our first objective is clear: not to screw up. Therefore, we focus more on the foundations, the things that we must be clear about before committing our money.
One of those things is what we want to achieve with our investment. Probably the person who invests in Bitcoin does not do it to ensure a quiet retirement. Their goal is different. Nor will a person who is looking for a house to buy behave the same as one who already has it or lives in rent. Nor will a 25-year-old take into account the same things as a 65-year-old.
That’s why it’s essential to know where we start from – and to get our finances in order. Having our investment objectives clear will also help us make better decisions. For example, if we are investing with a 20-year horizon – because we know that the long term is our friend – we will be more patient when things go less well. And we will not divest lightly, nor will we give up potential future profits.
Planning investments well is not just a matter of risk. It is to have a margin of safety. There is no closed definition, but, in essence, it is about having “an austere budget, a flexible mindset or a lax chronology” that, as Morgan Housel explains, “allows you to live happily with a wide variety of results.” That is, a framework that increases our chances of succeeding with the level of risk we have previously set.
The Rule of 72
It is not always easy to calculate the foreseeable or estimated result of our investments. Therefore, when planning it is useful to use the so-called rule of 72. This formula allows us to estimate how long, in years, it will take for our investment to double. Mind you, the rule of 72 is an approximation, not a mathematical law:
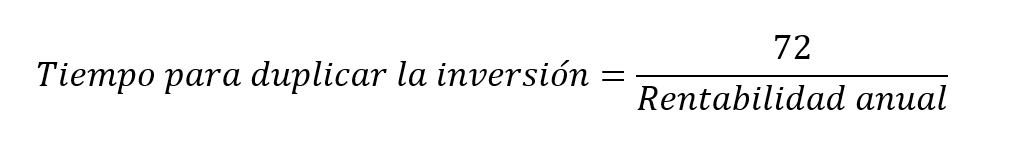
Imagine that we invest 1,000 euros in a product whose annual return is 4%. To estimate when those 1,000 euros will have become 2,000, it would be enough to divide 72 by 4 (the amount invested is not relevant). So if we want to double our money with that product we must maintain our investment in that product for 18 years.
This rule could also be used, with caution, to estimate the impact of inflation on our savings. In this case, we would try to find out how long it would take our money to divide between two: that is, to lose half of its value. The operation, in this case, would be somewhat different. 72 would have to be divided by the annual rate of inflation. For inflation of 4%, the result would also be 18 years. It is very approximate, since it is rare for inflation to be so stable for so long. But it serves to give us an idea.
Autonomy and financial freedom
Another way to approach our planning is to think in terms of financial freedom. That is, the degree of dependence or autonomy we have with respect to our salary. I’ll put it another way. It is assumed that full financial freedom is achieved when one can live on rents, that is, one does not need to work to obtain the income he needs to lead the life he wants to lead.
Perhaps it is a goal within the reach of a few. That is why we also talk about autonomy or financial independence. The idea is always the same, to see how we can balance our recurring income (payroll) and additional income (rental income, dividends, capital gains …). Investment is a good way to increase additional income and, therefore, improve our financial independence.
For example, in Urbanitae we offer you the possibility of obtaining periodic income with our new line of assets in profitability. It’s one more idea you can take a look at. Do the math and ask us what you want. That’s what we’re for…



