
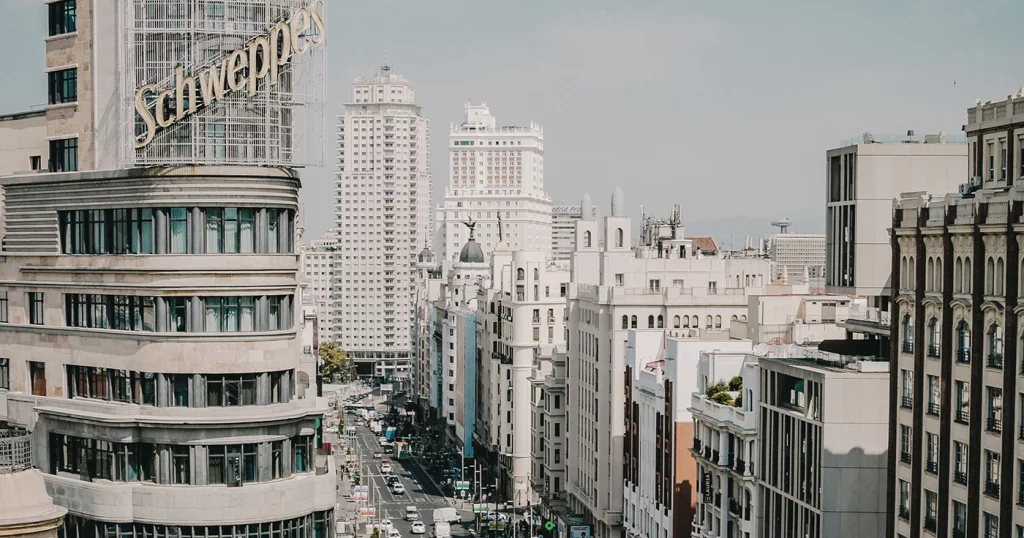
The transformation of retail has not diminished the appeal of the best shopping streets. Quite the opposite: along many major urban retail corridors, the availability of retail units remains extremely limited, brands compete for specific locations and investors continue to show interest in a type of property that is difficult to replicate.
The High Street 2024 Report by Gesvalt and aRetail, published in 2025, helps explain why. The study examines the main shopping streets in Spanish and Portuguese cities using variables such as footfall, occupancy, rents and the yields required by buyers.
The conclusion is not that every retail property is attractive, but that the best assets in the best stretches of a shopping street have very different characteristics from secondary retail.
What makes a prime retail property different?
In retail, prime does not simply mean being located in a city centre.
The best locations combine high footfall, visibility, accessibility, purchasing power, a concentration of retailers and a limited supply of comparable units. Micro-location also matters: two properties on the same street may perform very differently depending on the particular stretch, shopfront or pedestrian flow.
This combination explains why some shopping streets maintain particularly high occupancy rates.
In Madrid, for example, Preciados and Fuencarral had no vacant units in the sample analysed by Gesvalt, while Serrano recorded a vacancy rate of just 1%.
In Barcelona, Passeig de Gràcia also had a vacancy rate of approximately 2%.
Limited supply is part of the value
One of the defining features of high street retail is how difficult it is to increase the supply of genuinely prime locations.
New retail corridors may emerge and buildings can be refurbished, but replicating a location with the same footfall, visibility and concentration of brands is far from straightforward. This scarcity helps explain why certain properties continue to attract both retailers and investors.
Moreover, strong demand does not necessarily translate into a large number of transactions.
In Bilbao, for example, Gesvalt notes that transactions on Gran Vía have been very limited because much of the property ownership remains concentrated in a few hands. A similar situation can be seen on Marqués de Larios in Málaga, where the shortage of available properties limits transaction activity despite investor interest.
Therefore, low transaction volumes may reflect a shortage of supply rather than a lack of demand.
Quality is also reflected in the price
The appeal of the best locations comes with a trade-off: buyers are generally prepared to accept a lower initial yield.
The report places indicative yields on Serrano at around 3.3%–3.5%, while those on Passeig de Gràcia range from approximately 3.3% to 3.75%. On other shopping streets, investors require higher yields: Pelai, for example, stands at 4.25%–4.75%.
In Madrid, the report itself identifies transactions on Serrano completed at yields of around 3.4%. This yield compression reflects the price investors are willing to pay for attributes such as location, scarcity and property quality.
That is why a highly sought-after property does not necessarily offer a higher initial yield. Often, the opposite is true.
Physical stores do more than generate sales
Demand for these properties does not depend exclusively on sales made inside the shop.
For many brands, a store in a prime location also provides visibility, strengthens positioning and helps build customer relationships. This explains the proliferation of flagship stores, expansions and relocations along leading shopping streets.
The report highlights, for example, new openings and expansions on Passeig de Gràcia, as well as strong interest from international brands in specific streets in Madrid and Barcelona.
E-commerce has not eliminated this role. In many cases, the physical store is part of an omnichannel strategy in which the premises also serve as a showcase for the brand.
The tenant and lease matter as much as the street
From an investor’s perspective, location alone is not enough.
Two similar retail units can have very different values depending on the retailer occupying them, the lease term, the current rent, the guarantees and the rent review provisions.
It also matters whether the rent is sustainable. A high rent may appear attractive while the lease remains in force, but if the tenant leaves and the market cannot support that rent level, the property’s value may be affected.
Analysing retail property therefore means assessing both the real estate itself and the quality of the income stream it generates.
Prime does not mean a good investment at any price
Gesvalt’s figures show that the best shopping streets continue to offer characteristics that are difficult to find in other properties: high occupancy, limited supply and strong retailer demand.
However, those same characteristics are often reflected in high prices and compressed yields.
The main investment lesson is therefore similar to that of other real estate segments: a strong market does not make every property a good investment.
In high street retail, the city matters, but so does the street. The street matters, but so does the particular stretch. And once the property has been selected, the tenant, lease, rent and purchase price remain decisive.
That is precisely the difference between buying a retail unit and acquiring a genuinely prime asset.



